
Investor Relations


-
 5 Step Guide To Ease The Home Loan Process
Follow this 5-step home loan guide to understand eligibility, application, approval and disbursement for a smooth loan journey.
-
 Rules for Loan Against Property: Eligibility & Tips
Read the latest insights from Sammaan Capital.


- 5 Step Guide To Ease The Home Loan Process
Follow this 5-step home loan guide to understand eligibility, application, approval and disbursement for a smooth loan journey.
- Rules for Loan Against Property: Eligibility & Tips
Read the latest insights from Sammaan Capital.


- 5 Step Guide To Ease The Home Loan Process
Follow this 5-step home loan guide to understand eligibility, application, approval and disbursement for a smooth loan journey.
- Rules for Loan Against Property: Eligibility & Tips
Read the latest insights from Sammaan Capital.
About Us


All you need to know
- 5 Step Guide To Ease The Home Loan Process
Follow this 5-step home loan guide to understand eligibility, application, approval and disbursement for a smooth loan journey.
- Rules for Loan Against Property: Eligibility & Tips
Read the latest insights from Sammaan Capital.
Products


All you need to know
- 5 Step Guide To Ease The Home Loan Process
Follow this 5-step home loan guide to understand eligibility, application, approval and disbursement for a smooth loan journey.
- Rules for Loan Against Property: Eligibility & Tips
Read the latest insights from Sammaan Capital.
Calculators


All you need to know
- 5 Step Guide To Ease The Home Loan Process
Follow this 5-step home loan guide to understand eligibility, application, approval and disbursement for a smooth loan journey.
- Rules for Loan Against Property: Eligibility & Tips
Read the latest insights from Sammaan Capital.

Home Loan Eligibility Based on Salary: Salaried vs Self Employed
When you apply for a home loan, one of the first things a lender works out is your home loan eligibility based on salary or, if you run your own business, your income. How that is assessed differs a little between a salaried person and a self-employed one, and knowing where you stand helps you prepare the right way.


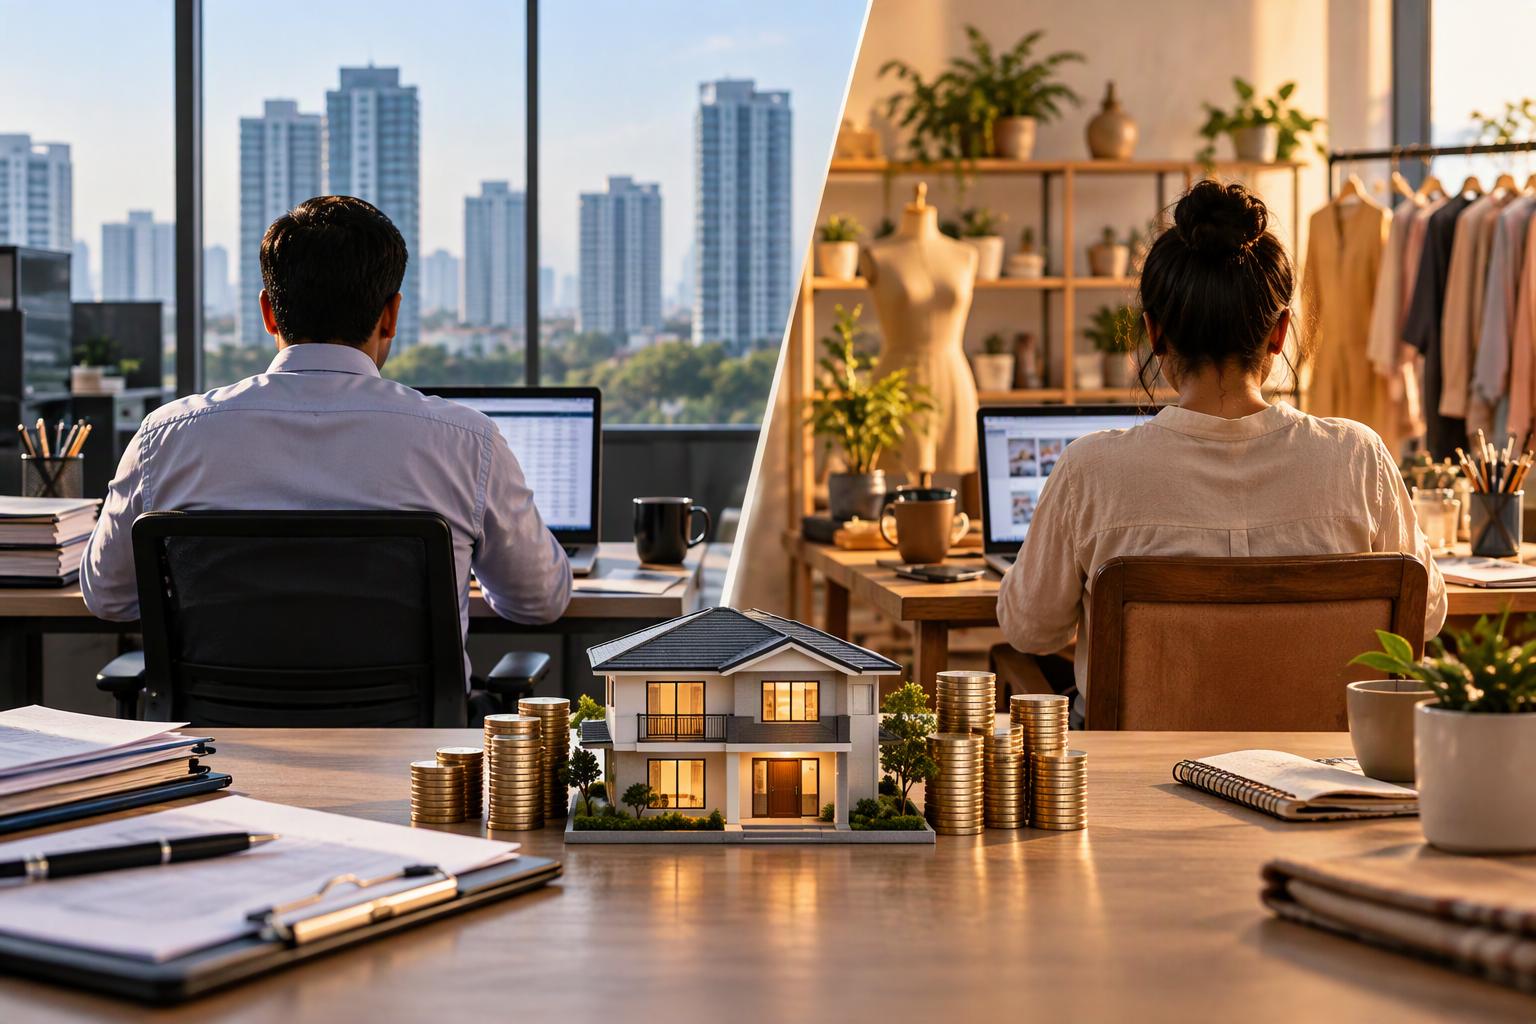
Table of Content
What Decides Your Home Loan Eligibility? Home Loan Eligibility for a Salaried Person Home Loan for Self Employed Applicants How Much Can You Borrow on Your Salary? Key Differences in Eligibility Between Salaried vs Self Employed Borrowers How to Strengthen Your Eligibility Irrespective of Your Income? The Right Fit for Your Income FAQs
What Decides Your Home Loan Eligibility?
Whatever you do for a living, home loan lenders check a similar set of things: your income and how steady it is, the EMIs and obligations you already carry, your credit score and repayment record, your age and the tenure you choose, and the value of the property you are buying. Your income shows your ability to repay, while your credit profile shows how reliably you have repaid in the past. The difference between a salaried person and a self-employed one is mostly in how that income is measured, not in the basic principle.
Home Loan Eligibility for a Salaried Person
Home loan for salaried person applicants and eligibility is relatively easy to assess, because the income arrives in a predictable pattern each month. Lenders look at your monthly take-home pay, how long you have been employed, and the stability of your employer, alongside your credit history. They then apply a simple test of affordability: the total of all your EMIs, existing ones plus the proposed home loan, should stay within a comfortable share of your net monthly income. That share is often in the range of 40% to 55%, with higher earners usually allowed to commit a little more, which is why your take-home salary has such a direct bearing on how much you can borrow.
Home Loan for Self Employed Applicants
A home loan for self employed applicants works on the same principle, with one key difference: your income is read from your business rather than a payslip. Lenders assess it through your income tax returns, audited financial statements, business bank statements, and how long your business has been running, looking at the trend over a few years rather than a single month. Because this income can rise and fall, consistency and clean records count for a great deal.
This is an area where Sammaan Capital, an RBI-regulated housing finance company, is especially accommodating. Eligible self-employed applicants may be considered under applicable surrogate or programme-based income assessment routes, subject to programme-specific eligibility, documentation, and credit norms. In practice, that means your genuine cash flow can be recognised in more than one way, which often makes self employed home financing more accessible than many business owners expect.
How Much Can You Borrow on Your Salary?
Your eligibility for a home loan based on salary really comes down to that one affordability test, and it is easiest to picture with an example. Suppose your net monthly salary is ₹60,000 and the lender allows you to put up to 55% of it towards EMIs. That is an EMI capacity of about ₹33,000 a month, and if you have no other loans running, an EMI of that size could support a home loan of roughly ₹37 lakh over a 20-year tenure at around 8.75%. Any EMIs you already pay are deducted from that capacity first, so clearing a small loan before you apply can noticeably lift how much you qualify for. An online eligibility or EMI calculator lets you try your own figures in seconds.
Key Differences in Eligibility Between Salaried vs Self Employed Borrowers
The table below sums up where the two paths differ, so you know what to prepare.
| What Lenders Check | Salaried Home Loan Borrower | Self-employed Home Loan Borrower |
|---|---|---|
| How income is assessed | Monthly salary and employer stability | Business income over time, read from returns and financials |
| Main income proof | Salary slips, Form 16, salary-account statements | Income tax returns, audited financials, business bank statements |
| What strengthens the case | Steady pay and length of service | Business vintage and consistent cash flow |
| Income assessment routes | Standard salary-based assessment | Standard, plus programme-based or surrogate routes |
How to Strengthen Your Eligibility Irrespective of Your Income?
A little groundwork improves your position no matter how you earn. These are the points worth acting on before you apply:
- Keep your credit score healthy. Pay your EMIs and card bills on time, since a strong CIBIL score helps your approval and your rate.
- Keep existing EMIs in check. Lower outstanding obligations free up more of your income for a new home loan.
- Consider an earning co-applicant. Adding a spouse or parent who earns can raise the amount you qualify for.
- Keep your records clean and ready. Tidy bank statements and up-to-date returns matter especially for self-employed applicants.
- Choose a comfortable tenure. A longer tenure lowers the EMI and can improve eligibility, as long as it suits your age and plans.
The Right Fit for Your Income
Whether your income comes as a monthly salary or from a business you have built, a home loan is well within reach once you understand how your eligibility is judged. Prepare the right documents, keep your obligations manageable, and pick a loan amount and tenure that sit comfortably with your earnings, and the path to your own home becomes a good deal clearer.
Frequently Asked Questions
How much can I borrow based on my salary?
As a rough indication, lenders let you put up to around 40% to 55% of your net monthly income towards all your EMIs combined, with the higher end usually reserved for higher earners. For example, a net salary of ₹60,000 with no other loans might support an EMI of about ₹33,000, which could fund a home loan of roughly ₹37 lakh over 20 years at around 8.75%. Any existing EMIs reduce this, so an eligibility or EMI calculator is the easiest way to get a figure for your own situation.
Can a self-employed person get a home loan as easily as a salaried one?
Yes. The main difference is in the paperwork: a self-employed applicant's income is assessed from income tax returns, financial statements, and business bank records rather than salary slips. Steady business income, a good credit score, and clean documentation make the process smooth, and programme-based assessment routes can help where income varies.
What documents are needed for salaried and self-employed applicants?
A salaried applicant typically provides salary slips, Form 16, and salary-account bank statements. A self-employed applicant provides income tax returns, audited financial statements, business proof such as registration or licences, and business bank statements. Both also submit identity and address proof (KYC) and the property documents.
Does being salaried or self-employed change my interest rate?
Your rate is driven mainly by your credit profile, income stability, and loan details rather than your employment type alone. A strong, well-documented profile can earn a competitive rate whether you are salaried or self-employed.
Share This Article


Explore Popular Blogs
Explore Other Categories

A-34, 2nd & 3rd Floor, Lajpat Nagar - II, New Delhi - 110024


100% safe and secure


Our Dedicated Support


100% safe and secure