
Investor Relations
-
 5 Step Guide To Ease The Home Loan Process
Follow this 5-step home loan guide to understand eligibility, application, approval and disbursement for a smooth loan journey.
-
 Rules for Loan Against Property: Eligibility & Tips
Read the latest insights from Sammaan Capital.
- 5 Step Guide To Ease The Home Loan Process
Follow this 5-step home loan guide to understand eligibility, application, approval and disbursement for a smooth loan journey.
- Rules for Loan Against Property: Eligibility & Tips
Read the latest insights from Sammaan Capital.
- 5 Step Guide To Ease The Home Loan Process
Follow this 5-step home loan guide to understand eligibility, application, approval and disbursement for a smooth loan journey.
- Rules for Loan Against Property: Eligibility & Tips
Read the latest insights from Sammaan Capital.
About Us
All you need to know
- 5 Step Guide To Ease The Home Loan Process
Follow this 5-step home loan guide to understand eligibility, application, approval and disbursement for a smooth loan journey.
- Rules for Loan Against Property: Eligibility & Tips
Read the latest insights from Sammaan Capital.
Products
All you need to know
- 5 Step Guide To Ease The Home Loan Process
Follow this 5-step home loan guide to understand eligibility, application, approval and disbursement for a smooth loan journey.
- Rules for Loan Against Property: Eligibility & Tips
Read the latest insights from Sammaan Capital.
Calculators
All you need to know
- 5 Step Guide To Ease The Home Loan Process
Follow this 5-step home loan guide to understand eligibility, application, approval and disbursement for a smooth loan journey.
- Rules for Loan Against Property: Eligibility & Tips
Read the latest insights from Sammaan Capital.

What is a Home Loan Amortization Schedule and How to Calculate it?
Your EMI stays the same each month, but the way it is split between interest and principal changes over the life of the loan. A home loan amortization schedule sets this out clearly, and this guide explains what it is, how to read it, and how to calculate your own.
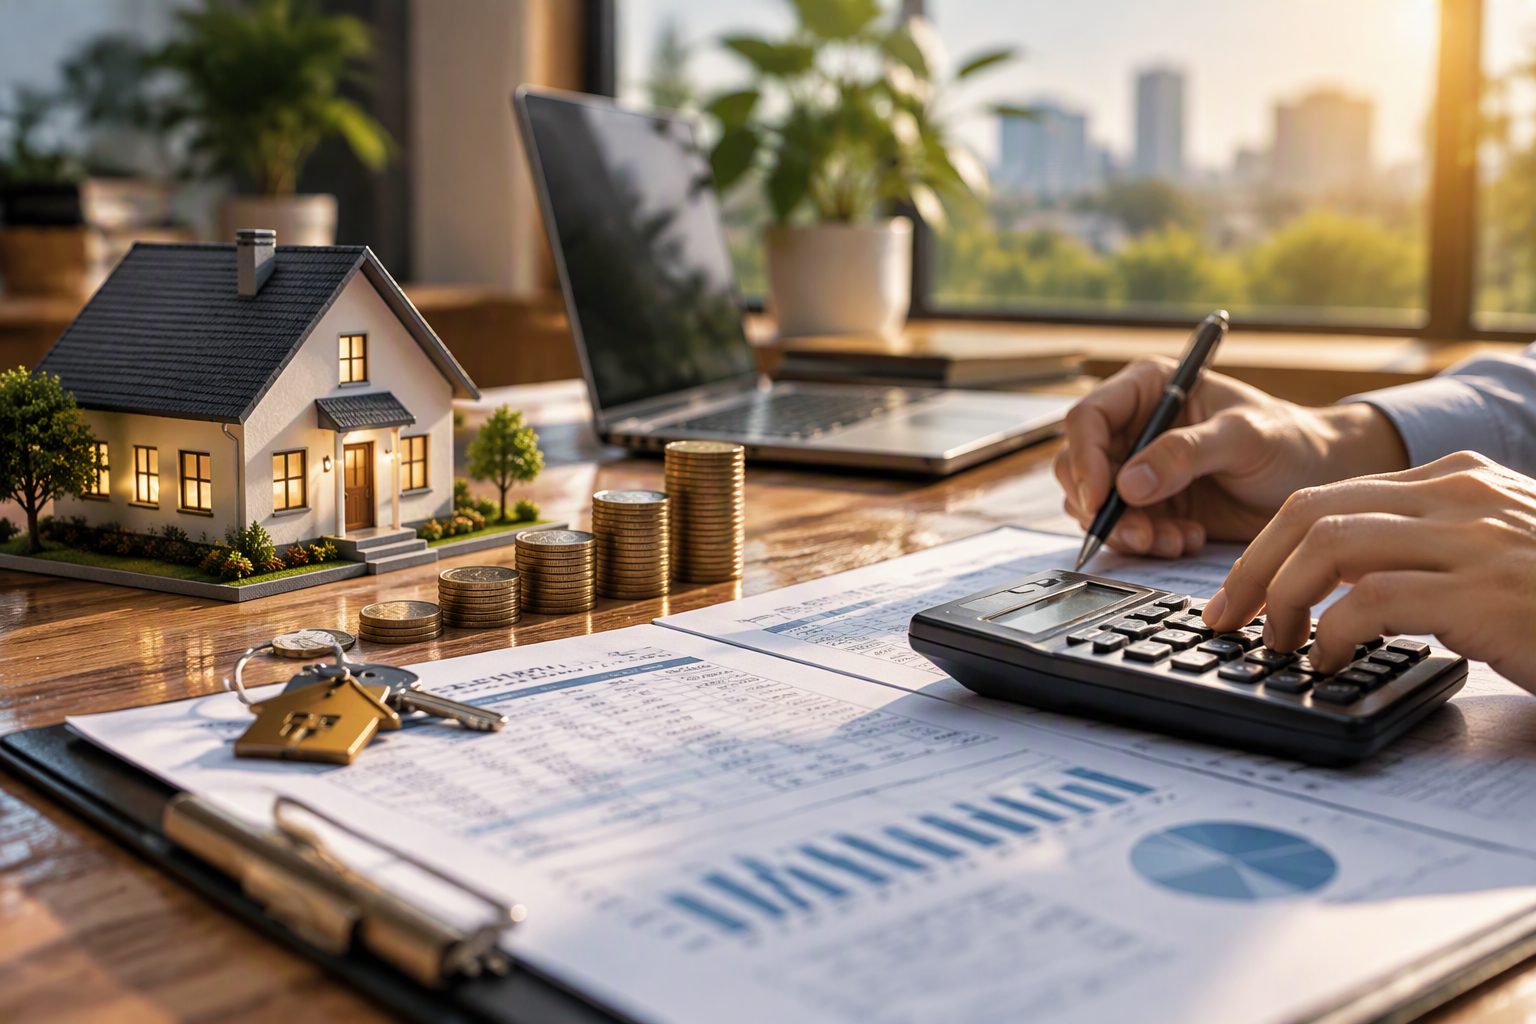
Table of Content
What is a Home Loan Amortization Schedule? How Does an Amortization Schedule Work? Key Components of an Amortization Schedule How to Calculate Your Amortization Schedule? Why Understanding Your Amortization Schedule Helps? Do Floating Rates Affect Home Loan Amortization Schedule? How Can I Get My Amortization Schedule? Final Thoughts! FAQs
What is a Home Loan Amortization Schedule?
A home loan amortization schedule is a detailed, month-by-month table of your entire repayment, from your first EMI to your last. For every month, it divides your EMI into two parts, the interest you pay and the principal you repay, and shows the outstanding balance remaining after that payment.
Your lender usually provides this schedule when your loan is disbursed. It gives you a clear view of how your monthly payments reduce the amount you owe, and how much interest you pay over the term of the loan.
How Does an Amortization Schedule Work?
The idea behind it is simple: interest is charged on the balance you still owe. Because that balance is highest at the start, a larger share of your early EMIs goes towards interest, and this share gradually moves towards principal over the years.
- In the early years: A large part of each EMI goes towards interest, because your outstanding balance is at its highest. The principal comes down slowly at this stage, which is completely normal.
- Through the middle years: As the balance falls, the interest portion of each EMI shrinks and more of your money starts going towards the principal.
- In the final years: Most of your EMI now goes towards the principal, the interest portion is small, and your balance reduces quickly towards zero.
Key Components of an Amortization Schedule
Every amortization table is built from the same few columns, and once you know what each one means, the whole schedule becomes easy to read.
- EMI amount: The fixed sum you pay each month, made up of both principal and interest.
- Interest component: The share of each EMI that goes towards interest, highest early on and reduces steadily as your balance falls.
- Principal component: The share that reduces the amount you borrowed, small at first and growing larger with every EMI.
- Outstanding balance: The amount you still owe after each payment, reducing month by month until it reaches zero.
How to Calculate Your Amortization Schedule?
The calculation is simpler than it may appear. It begins with your EMI, and a short, repeating step then builds the rest of the schedule.
Step 1: Calculate your EMI
Your home loan EMI is calculated using this formula:
EMI = P x R x (1 + R)^N / ((1 + R)^N - 1)
Here, P is your loan amount (the principal), N is the number of monthly instalments (your tenure in months), and R is your monthly interest rate, which is the annual rate divided by 12 and then by 100.
Step 2: Divide EMI into interest and principal
For any given month, the amortization calculation is:
Interest for the month = outstanding balance x monthly rate (R)
Principal for the month = EMI minus that interest
New outstanding balance = previous balance minus that month's principal
You repeat this every month, and the result is your full amortization schedule.
Understand with an example
Consider a home loan of ₹30 lakh at a floating rate of 8.75%* p.a. over 20 years. The EMI is approximately ₹26,511. The first three months are shown below.
| Month | EMI (₹) | Interest (₹) | Principal (₹) | Outstanding balance (₹) |
|---|---|---|---|---|
| 1 | 26,511 | 21,875 | 4,636 | 29,95,364 |
| 2 | 26,511 | 21,841 | 4,670 | 29,90,694 |
| 3 | 26,511 | 21,807 | 4,704 | 29,85,990 |
In these early months, most of the EMI goes towards interest and only a small part reduces the principal. Several years later, the same ₹26,511 EMI is divided the other way, with most of it going towards principal and only a small part towards interest. Calculating this manually for all 240 months would take considerable time, so it is easier to use a home loan EMI calculator, which prepares the full schedule for you in seconds.
Figures are indicative and rounded, for illustration only. Your actual EMI and schedule depend on the loan amount, the applicable rate, and your profile.
Why Understanding Your Amortization Schedule Helps?
Reading your schedule is more than a formality. It gives you a clear understanding of your loan and helps you manage it well.
- Better budgeting: Knowing exactly what you owe each month helps you plan your household budget and savings with confidence.
- Interest cost clarity: Seeing how much of your early EMIs go towards interest often encourages borrowers to plan ahead and reduce it where possible.
- Record your progress: Tracking how the outstanding balance reduces month after month gives you a clear sense of your progress in repaying the loan.
- Better prepayment planning: The schedule shows the effect of a prepayment, so you can use any surplus funds to reduce your balance and your total interest.
- Easier cross-checking: You can compare the schedule with your loan statements to confirm your EMIs are being applied correctly.
Do Floating Rates Affect Home Loan Amortization Schedule?
Home loans at Sammaan Capital carry a floating interest rate, which is linked to a benchmark and can move up or down over time. Because of this, your amortization schedule is based on your current rate, and it is revised whenever the benchmark rate changes. When the rate changes, your lender typically adjusts either your EMI or your tenure, and a revised schedule reflects the new position. It is advisable to review your updated schedule after any rate change, so you have an accurate picture of your repayment.
How Can I Get My Amortization Schedule?
You do not have to wait until you sign your loan agreement to see one. You can easily generate one online using a home loan EMI calculator. You enter your loan amount, the home loan interest rate, and the tenure, and it produces a year-wise and month-wise schedule. This is a useful way to compare different tenures and see how a prepayment could affect your repayment before you decide.
Final Thoughts!
An amortization schedule gives you a clear view of your home loan and how it will be repaid. Once you understand how each EMI is split and how your balance reduces, you can budget with confidence, plan your prepayments well, and stay in control of your loan from start to finish.
Frequently Asked Questions
What is a home loan amortization schedule?
It is a month-by-month table of your entire loan repayment. For each EMI, it shows how much goes towards interest, how much reduces the principal, and the outstanding balance remaining after that payment, up to the final instalment.
How is an amortization schedule calculated?
It begins with your EMI, which is calculated from your loan amount, interest rate, and tenure. For each month, the interest is your outstanding balance multiplied by the monthly rate, the principal is the EMI minus that interest, and the balance reduces by that principal. This repeats every month until the loan is fully repaid.
Why is the interest portion higher in the early years?
Because interest is charged on the balance you still owe, and that balance is at its highest at the start. As you continue repaying, the balance falls, so the interest portion of each EMI reduces and a larger part goes towards the principal.
Does making a prepayment change my amortization schedule?
Yes. A prepayment reduces your outstanding principal, which lowers the interest charged from that point onwards. Depending on the option you choose, this can shorten your tenure or reduce your EMI. Any applicable charges are levied as per applicable regulatory guidelines and company policy.
Does my amortization schedule change if my interest rate changes?
Yes. With a floating-rate loan, the schedule is revised whenever the benchmark rate changes. Your lender usually adjusts your EMI or your tenure, and an updated schedule reflects the new rate, so it is worth reviewing it after any change.
Can I get my amortization schedule online?
Yes. Most lenders provide it with your loan documents, and you can also generate one using a home loan EMI calculator by entering your loan amount, interest rate, and tenure.
Share This Article


Explore Popular Blogs
Explore Other Categories

A-34, 2nd & 3rd Floor, Lajpat Nagar - II, New Delhi - 110024


100% safe and secure


Our Dedicated Support

100% safe and secure